Capacity Europe 2026: Tackling constraints sets the agenda
Author: Joe Peck
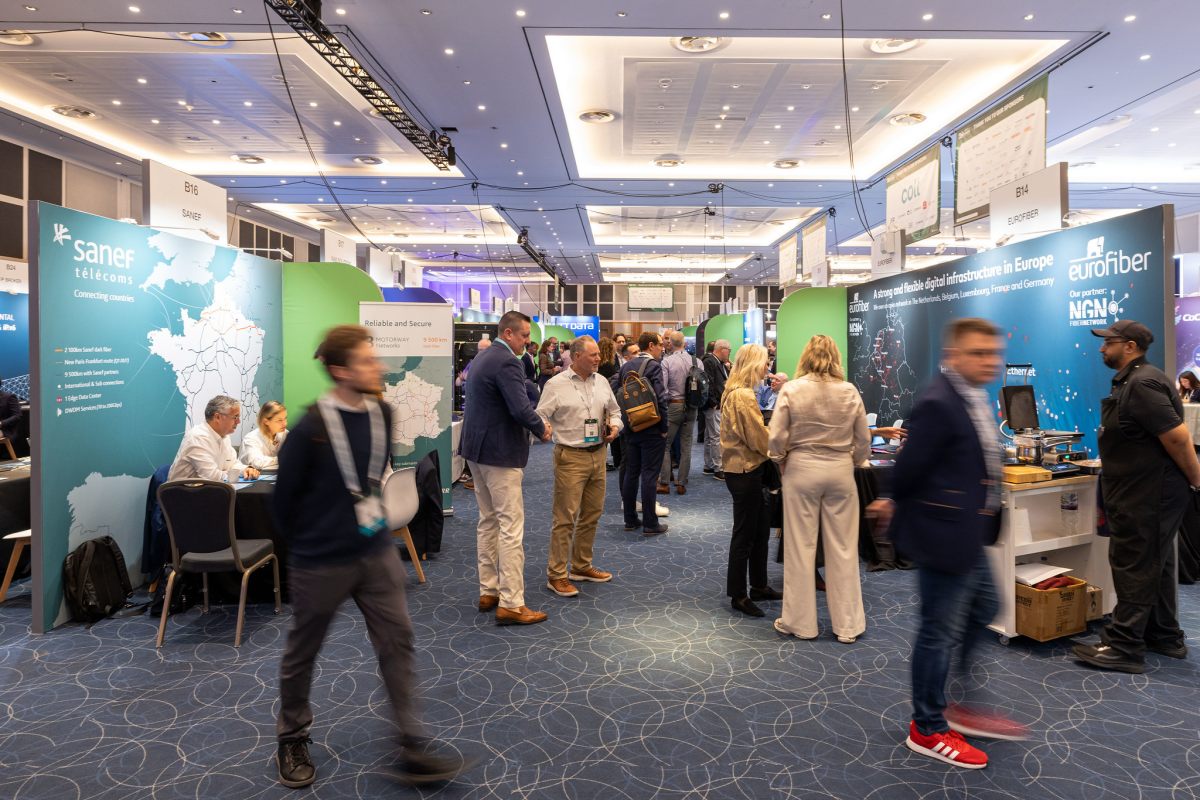
This October, Capacity Europe, an event for global digital infrastructure and connectivity, marked its 25th anniversary at the InterContinental London – The O2, bringing together more than 3,500 decision makers from across the connectivity and digital infrastructure community.
As DCNN observed, speaking to a wide spectrum of those present whilst at the event, AI demand was largely taken as self-evident. The more pressing discussions centred on what stands between that demand and its delivery, with key talking points being around power, grid timelines, equipment, skilled labour, community consent, and the discipline of the capital funding it all.
Key takeaways
Machines overtake humans
On the Market Forces Stage, Colt’s Avijit Singh opened with data from Cloudflare showing that machine-generated web requests overtook human ones for the first time in June, at 57.4% to 42.6%.
Machine traffic could exceed human traffic by 100 times within five years, he said, shifting the emphasis from north–south traffic towards east–west flows between agents and data centres. That raises the bar for latency, resilience, automation, and observability, and moves security towards verifying machine identity rather than users.
Inference and the edge
Several speakers at the event identified inference, rather than training, as the next wave of compute.
Verizon’s Jeff Hulse cited McKinsey research suggesting that 2026 is the first year in which inference investment matches training, whilst DE-CIX’s Ivo Ivanov noted that each millisecond of latency equates to roughly 80km, placing agentic and physical AI applications within 100km to 150km of the inference they depend on.
The result is renewed demand for edge locations and a European data centre map spreading well beyond FLAP-D.
Supply chains and grid certainty
Securing supply emerged as a bigger concern than price. Telehouse’s Ozgur Duzgunoglu said generators can take two years to arrive and high-voltage transformers 12 to 18 months, prompting operators to commit to suppliers before designs are final.
On power, the issue was less availability and more predictability, with one investor describing grid operators promising connections in 36 months and delivering in 48. National Grid’s David Atkins said the UK transmission owner is building three times as much network in this five-year period as in the last, and that flexibility of just 1% to 2% from data centres could unlock significant spare capacity.
Capital, risk, and social licence
The AI Build Stage hosted ‘Capital at Risk: Navigating investment and returns in the AI Era’, chaired by the Data Centre Alliance’s Venessa Moffat. Panellists from BGO Data Centers, DigitalBridge, Guggenheim, and Echelon Data Centres agreed that the underlying risks are familiar, but they are magnified by the speed and scale of investment.
Underwriting standards must adapt, they said, to faster equipment upgrade cycles and a broader investor base that now includes pension and sovereign wealth funds. DigitalBridge’s Zach Gellman was emphatic on community acceptance, stating, “Social licence is 100% critical.”
Connectivity and the Fibre Investment stage
Connectivity featured as a recurring warning against late planning. Digital Realty’s Paula Cogan said network planning still comes too late in many builds, and Salam’s Amjad Arab said AI workloads can need up to 36 times more fibre than traditional applications.
FLAG’s Paul Abfalter described significant underinvestment in long-haul links between data centres, whilst Orange announced a joint venture to deliver Pisces, a subsea system linking Ireland, France, Spain, and Portugal without transiting the UK.
On the Fibre Investment stage, nexfibre’s Rajiv Datta challenged the CMA’s provisional findings on the £2 billion Netomnia acquisition, with the regulator’s final decision due by 15 December.
Where will value land?
The closing panel, ‘Digital Infrastructure in 2029: Who Captures the Next Wave of Value?’, brought together speakers from FLAG, ING, Mobile UK, and LINX. ING’s Jeroen Kleinjan offered the clearest answer: “Value will accrue around bottlenecks”, which he named as power, strategic sites, scarce routes, and trusted interconnection.
Meanwhile, Mobile UK’s Hamish MacLeod noted that UK mobile revenues have fallen by about 30% while traffic has grown 40 times, a reminder that growth alone does not guarantee returns.
For more on Capacity Europe, click here.